Metrobank Personal Loan 2026: Requirements, Rates and Application Guide
Kailangan mo ba ng extra cash para sa medical expenses, tuition, home renovation, wedding, debt consolidation, o iba pang malaking gastusin?
Isa sa mga puwedeng pagpilian sa Pilipinas ang Metrobank Personal Loan.
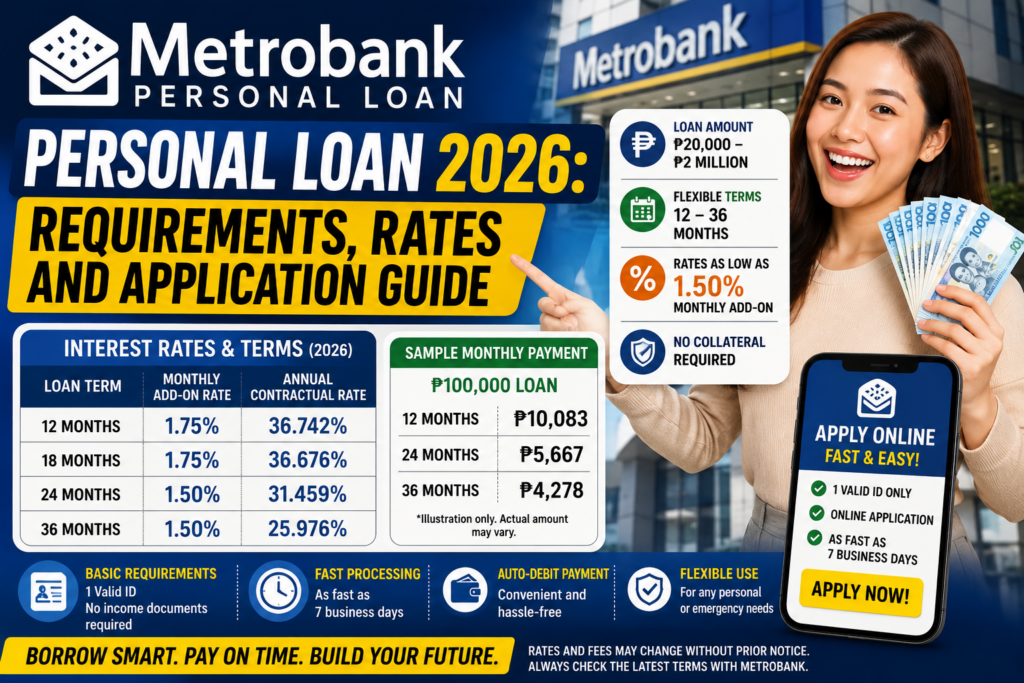
Ang loan amount ay maaaring mula ₱20,000 hanggang ₱2 million, may payment terms hanggang 36 months, at hindi kailangan ng collateral.
Pero bago mag-apply, mahalagang malaman ang interest rate, requirements, monthly payment, fees, at eligibility rules.
Narito ang updated guide sa Metrobank Personal Loan 2026.
Metrobank Personal Loan 2026: Quick Overview
Narito ang pangunahing features:
Loan Amount: ₱20,000 hanggang ₱2,000,000
Loan Terms: 12, 18, 24, o 36 months
Collateral: Not required
Minimum Gross Annual Income: ₱250,000
Application: Online
Basic Document: 1 valid ID
Processing: As fast as 7 business days
Ang final loan amount at approval ay nakadepende pa rin sa credit evaluation ng Metrobank.
Magkano ang Metrobank Personal Loan Interest Rate?
Ayon sa current Metrobank Personal Loan Rates & Fees information, ang published rates ay:
| Loan Term | Monthly Add-on Rate | Annual Contractual Rate |
|---|---|---|
| 12 months | 1.75% | 36.742% |
| 18 months | 1.75% | 36.676% |
| 24 months | 1.50% | 31.459% |
| 36 months | 1.25% | 25.976% |
Importanteng tandaan:
Hindi pareho ang monthly add-on rate at tunay na annual cost ng loan.
Halimbawa, ang 1.50% monthly add-on rate ay hindi nangangahulugan na simpleng 18% lamang ang actual annual borrowing cost.
Kaya bago tanggapin ang loan, tingnan ang Annual Contractual Rate, APR/Effective Interest Rate, monthly amortization, fees, at total repayment.
Rates are also subject to change, kaya i-check ang final offer at Disclosure Statement bago pumirma.
Sample: ₱100,000 Metrobank Personal Loan
Using the published add-on rates above, the Metrobank loan terms give this calculation: Interest = principal × monthly add-on rate × months; monthly amortization = (principal + interest) ÷ months.
| Term | Approx. monthly payment | Total add-on interest | Scheduled repayments: principal + interest |
|---|---|---|---|
| 12 months | ₱10,083.33 | ₱21,000 | ₱121,000 |
| 18 months | ₱7,305.56 | ₱31,500 | ₱131,500 |
| 24 months | ₱5,666.67 | ₱36,000 | ₱136,000 |
| 36 months | ₱4,027.78 | ₱45,000 | ₱145,000 |
The scheduled repayments exclude disbursement fees and other applicable charges. Monthly figures are rounded, so use the bank’s final amortization schedule for the exact installments. Sa mga halimbawang ito, mas mahaba ang tenor at mas maliit ang monthly payment, pero mas malaki ang total interest.
Before comparing a monthly installment with your salary, estimate your pay after mandatory deductions using our Philippines salary calculator. Compare that estimate with your actual payslip, regular household expenses and existing repayments; meeting the bank’s minimum gross income is separate from having money available each month.
Sino ang Qualified?
Para makapag-apply sa Metrobank Personal Loan, kailangan mong matugunan ang current eligibility criteria.
Basic Eligibility
Kailangan:
Filipino citizen
At least 21 years old at the time of application
Not more than 65 years old upon loan maturity
Gross annual income of at least:
₱250,000
At mayroon ding importanteng requirement:
You must have an existing credit card.
Metrobank’s current FAQ further states that applicants without a principal credit card need to become an existing principal credit cardholder for at least 9 months to qualify.
Requirements for Employed Applicants
Kung employed ka, kailangan mong:
Be a regular employee
at
Be with your current employer for at least 1 year.
Magandang feature ng current Metrobank Personal Loan application ay minimal ang documentary requirement.
Metrobank currently advertises:
No income documents required
at puwedeng mag-apply gamit ang:
1 valid ID
subject pa rin sa verification at credit evaluation.
Requirements for Self-Employed Applicants
Kung self-employed, kailangan:
At least 2 years in your current business.
Kailangan mo ring ma-meet ang ₱250,000 minimum gross annual income requirement at iba pang eligibility criteria.
Metrobank may verify information provided during the application and may request additional information when necessary.
Anong Valid ID ang Puwede?
Metrobank lists several acceptable IDs, including:
Philippine Identification Card / PhilID
Passport
Driver’s License
SSS Card / UMID
Postal ID
Voter’s ID
GSIS e-Card
Senior Citizen Card
PWD ID
at iba pang qualified government-issued identification.
Siguraduhing malinaw at valid ang ID na ia-upload mo.
Paano Mag-Apply sa Metrobank Personal Loan?
Isa sa magandang features ng Metrobank Personal Loan ay puwedeng gawin online ang application.
Step 1: Fill Out the Online Application
Pumunta sa official Metrobank Personal Loan application page at kumpletuhin ang online form.
Step 2: Upload Your Valid ID
Mag-upload ng clear scanned copy o photo ng iyong valid ID.
Step 3: Submit the Application
I-review ang information bago i-submit.
Make sure na tama ang:
Name
Contact information
Employment/business information
Income
at iba pang financial information.
Lahat ng information declared in the application may be subject to verification.
Gaano Katagal ang Approval?
Metrobank states that Personal Loan applications can be processed:
As fast as 7 business days.
Kapag may decision na sa online application, makakatanggap ang applicant ng notification via:
SMS
Tandaan na “as fast as 7 business days” ay hindi guarantee na lahat ng applications ay matatapos sa eksaktong pitong araw.
Processing time can vary depending on verification at credit evaluation.
Magkano ang Fees and Charges?
Hindi lamang interest ang dapat tingnan.
Disbursement Fee
Current Metrobank fee:
₱1,500
Documentary Stamp Tax
Para sa loans above ₱250,000:
0.75% of the loan amount
Halimbawa:
Kung ₱300,000 ang loan:
₱300,000 × 0.75% = ₱2,250
So bukod sa ₱1,500 disbursement fee, may ₱2,250 DST sa example na iyon.
Sa Metrobank terms, Section 2.6, ang ₱1,500 disbursement fee ay ibinabawas sa principal upon loan booking. Kung ₱100,000 ang approved principal at ito lamang ang deduction, ₱98,500 ang net loan proceeds. Ang repayment example sa itaas ay nakabatay pa rin sa ₱100,000 principal. Sa 12-month illustration, ang ₱121,000 scheduled repayments minus ₱98,500 cash received ay ₱22,500: ₱21,000 interest plus ₱1,500 fee. Confirm the actual deductions in your Disclosure Statement.
Late Payment Fee
Kung hindi makabayad on time, Metrobank currently lists:
₱850 per incidence of late payment or non-payment.
Kaya importanteng siguraduhing may sapat na balance sa payment account bago dumating ang due date.
Puwede Bang Bayaran Nang Maaga?
Yes, pero may applicable pre-termination fee.
Metrobank currently lists:
5% of the outstanding balance or ₱550, whichever is higher.
Kaya kung balak mong bayaran nang maaga ang loan, itanong muna sa bank kung magkano ang actual pre-termination amount.
Hindi automatic na walang additional cost ang early repayment.
Paano Binabayaran ang Monthly Loan?
Ang Metrobank Personal Loan amortization ay binabayaran through:
Auto-Debit Arrangement (ADA)
gamit ang Metrobank deposit account.
Kung wala ka pang Metrobank deposit account at approved ang loan, kailangan mong mag-open ng account para magamit sa loan payments.
Practical tip:
Huwag hintayin ang mismong due date bago maglagay ng pera.
Maintain enough balance sa account bago ang scheduled debit para maiwasan ang late payment.
Kailangan ba ng Collateral?
No.
Ang Metrobank Personal Loan ay isang unsecured personal loan.
Hindi mo kailangang magbigay ng bahay, lupa, o sasakyan bilang collateral.
Pero dahil walang collateral, mahalaga sa evaluation ang iyong financial profile.
Metrobank notes that factors such as credit history/credit score at debt-to-income situation can affect the assessment of a personal-loan application.
Para Saan Puwedeng Gamitin ang Loan?
Flexible ang personal loan kumpara sa home loan o car loan.
Metrobank states that it can be used for purposes such as:
Medical emergencies
Tuition fees
Home repairs or renovation
Wedding expenses
Large personal purchases
Debt consolidation
at iba pang unexpected expenses.
Pero kahit approved ka sa malaking amount, huwag automatic kunin ang maximum.
Borrow only what you actually need.
Metrobank Personal Loan: Pros and Things to Consider
Advantages
Loan amount up to ₱2 million
No collateral
Online application
Minimal documentary requirement
Terms up to 36 months
Processing as fast as 7 business days
Things to Consider
May existing credit-card requirement
May ₱1,500 disbursement fee
May DST for loans above ₱250,000
May late-payment fee
May pre-termination fee
At higit sa lahat, mas mataas ang tunay na annual borrowing cost kaysa sa maaaring ipahiwatig ng monthly add-on rate lamang.
Frequently Asked Questions
How much can I borrow from Metrobank?
The current Metrobank Personal Loan range is:
₱20,000 to ₱2 million
subject to credit evaluation.
What is the Metrobank Personal Loan interest rate in 2026?
Current published monthly add-on rates are:
1.75% for 12 and 18 months
and
1.50% for 24 months
and 1.25% for 36 months.
Rates are subject to change.
What salary do I need?
Metrobank currently requires at least:
₱250,000 gross annual income
which averages approximately ₱20,833 per month when simply divided by 12.
However, meeting the income requirement alone does not guarantee approval.
Do I need a credit card?
Yes. Metrobank currently requires an existing credit card, and its FAQ specifies that applicants without one need to establish at least 9 months as a principal credit cardholder before becoming eligible.
Do I need income documents?
Metrobank currently advertises its Personal Loan as requiring no income documents, with one valid ID for the online application. Information remains subject to verification and credit evaluation.
How long does approval take?
Metrobank states that processing can be completed as fast as 7 business days.
Do I need collateral?
No. Metrobank Personal Loan is an unsecured loan.
Final Takeaway
Ang Metrobank Personal Loan 2026 ay interesting option para sa qualified borrowers na kailangan ng ₱20,000 hanggang ₱2 million at gustong magbayad over 12 to 36 months.
Malaking advantage ang simple online application at minimal documentary requirement.
Pero may isang requirement na dapat malaman agad:
Kailangan ng existing credit card.
At bago magdesisyon, huwag monthly add-on rate lang ang tingnan.
Compare:
Monthly amortization
Annual contractual/effective rate
Total repayment
Disbursement fee
Documentary Stamp Tax
Late-payment fee
at pre-termination fee.
Kung magko-compare ka ng Metrobank, BDO, BPI, o ibang personal loans, gamitin ang parehong loan amount at parehong repayment period para patas ang comparison.
Borrow only what you need and what you can comfortably repay.
Disclaimer: This article is for general informational purposes only and does not constitute financial advice. Interest rates, fees, eligibility requirements and other loan terms may change. Approval and final terms are determined by Metrobank. Always verify the latest rates and review the Disclosure Statement before accepting a loan.
Sources
Metrobank Personal Loan Rates & Fees — Official current interest-rate table and fees
Information checked: August 29, 2026
Published rates and fees previously checked: October 11, 2026. Rate table, four-tenor repayment illustrations and disbursement-fee treatment reviewed: October 26, 2026. Confirm the terms in your own Disclosure Statement.


Comments 0
Be the first to comment..