BIR Income Tax Philippines 2026: Magkano ang Tax sa Sweldo?
Kapag nakikita mo ang withholding tax sa payslip mo, baka napapatanong ka:
“Bakit may tax ang sweldo ko?”
O baka mas importante:
“Magkano ba talaga ang income tax ko sa Philippines?”
Hindi pare-pareho ang tax ng lahat ng empleyado. Depende ito sa iyong taxable compensation income, at hindi ibig sabihin na kapag tumaas ang sweldo mo ay ita-tax agad ang buong amount gamit ang pinakamataas na rate.
Narito ang simpleng guide sa BIR income tax rates sa Philippines para sa 2026.
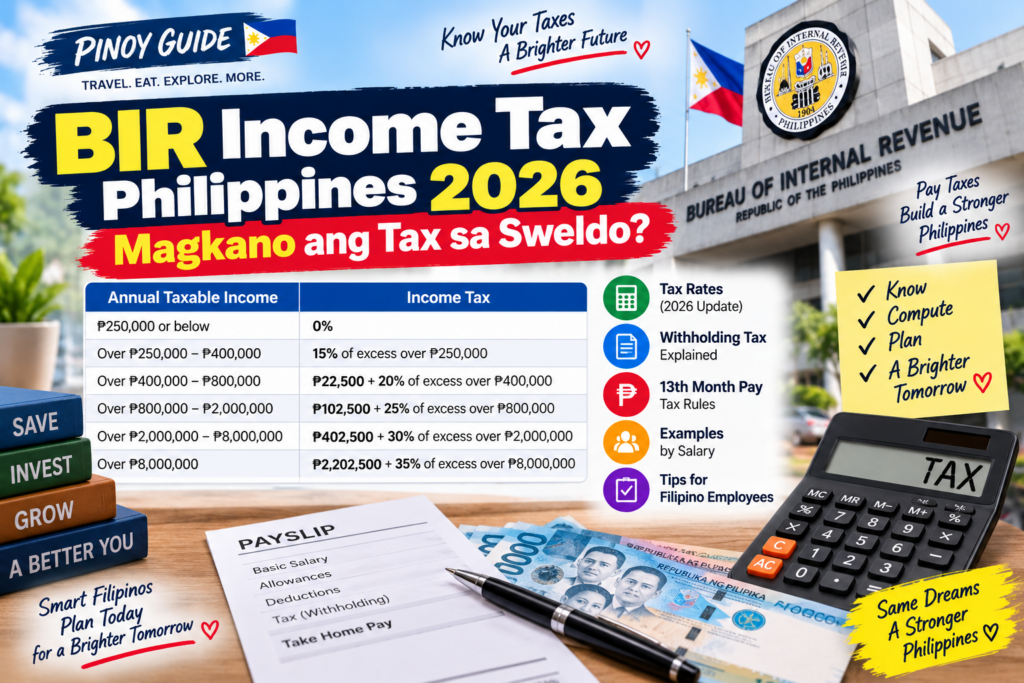
BIR Income Tax Rates for 2026
Under the tax rates effective from January 1, 2023 onwards, ito ang ginagamit na graduated income tax table for individual taxpayers.
| Annual Taxable Income | Income Tax |
|---|---|
| ₱250,000 or below | 0% |
| Over ₱250,000 – ₱400,000 | 15% of excess over ₱250,000 |
| Over ₱400,000 – ₱800,000 | ₱22,500 + 20% of excess over ₱400,000 |
| Over ₱800,000 – ₱2,000,000 | ₱102,500 + 25% of excess over ₱800,000 |
| Over ₱2,000,000 – ₱8,000,000 | ₱402,500 + 30% of excess over ₱2,000,000 |
| Over ₱8,000,000 | ₱2,202,500 + 35% of excess over ₱8,000,000 |
Ang mahalagang tandaan:
Hindi automatic na taxable ang buong gross salary mo.
Tax is calculated based on taxable income after applicable non-taxable compensation and mandatory employee contributions are taken into account. BIR’s withholding calculator specifically treats employee shares in SSS/GSIS, PhilHealth and Pag-IBIG among the relevant non-taxable deductions in determining taxable compensation.
Kung ₱20,000 ang Monthly Salary, May Income Tax ba?
Let’s start with a simple example.
Kung ₱20,000 ang monthly compensation:
₱20,000 × 12 = ₱240,000
That’s below the ₱250,000 annual taxable-income threshold.
So, in this simplified example—assuming annual taxable income, not merely gross salary, remains at or below ₱250,000:
Income Tax = ₱0
BIR’s current monthly withholding table likewise starts with ₱20,833 and below at zero withholding tax for the applicable taxable compensation range.
Pero tandaan: hindi sapat na tingnan lamang ang headline monthly salary. Bonuses, commissions, allowances and other taxable compensation can affect the final computation.
Example: ₱30,000 Monthly Taxable Compensation
Suppose your taxable compensation works out to approximately:
₱30,000 × 12 = ₱360,000
The annual taxable income falls within the:
Over ₱250,000 to ₱400,000 bracket.
Calculation:
₱360,000 − ₱250,000 = ₱110,000
₱110,000 × 15% = ₱16,500
Estimated annual income tax:
₱16,500
Notice that 15% was not charged on the entire ₱360,000.
Only the amount above ₱250,000 was subject to the 15% rate in this simplified example.
That’s how a graduated income tax system works.
Example: ₱50,000 Monthly Taxable Compensation
Let’s assume taxable compensation of:
₱50,000 × 12 = ₱600,000
This falls into the over ₱400,000 to ₱800,000 bracket.
The formula is:
₱22,500 + 20% of excess over ₱400,000
So:
₱600,000 − ₱400,000 = ₱200,000
20% of ₱200,000 = ₱40,000
Add ₱22,500:
Estimated annual tax = ₱62,500
Again, this is a simplified annual example intended to explain how the tax bracket works, not an exact payslip computation.
Bakit Iba ang Tax na Nakikita sa Payslip?
Employers normally deduct withholding tax on compensation from an employee’s payroll and remit it to BIR.
For monthly payroll, the BIR withholding table effective from January 1, 2023 onward uses these taxable-compensation ranges:
| Monthly Taxable Compensation | Withholding Formula |
|---|---|
| ₱20,833 and below | ₱0 |
| Over ₱20,833 to ₱33,332 | 15% of excess over ₱20,833 |
| ₱33,333 to ₱66,666 | ₱1,875 + 20% of excess over ₱33,333 |
| ₱66,667 to ₱166,666 | ₱8,541.80 + 25% of excess over ₱66,667 |
| ₱166,667 to ₱666,666 | ₱33,541.80 + 30% of excess over ₱166,667 |
| ₱666,667 and above | ₱183,541.80 + 35% of excess over ₱666,667 |
May separate BIR tables din for daily, weekly at semi-monthly payroll periods.
Kaya huwag basta gamitin ang monthly table kung ibang payroll period ang ginagamit sa iyong payslip.
Gross Salary vs Taxable Compensation
Ito ang isa sa pinaka-importanteng bagay na dapat maintindihan.
Gross salary ≠ automatically the same as taxable compensation.
BIR’s own withholding calculator distinguishes taxable regular and supplementary compensation from non-taxable/exempt compensation. It also accounts for mandatory employee contributions such as SSS/GSIS, PhilHealth and Pag-IBIG when determining taxable compensation.
For example, taxable supplementary compensation may include things like commissions, overtime pay and taxable bonuses, depending on the employee’s circumstances.
That’s why two people who appear to have similar basic salaries may not always see exactly the same withholding amount.
Paano ang 13th Month Pay?
May important tax benefit dito.
Under BIR rules reflected in its current withholding calculator, 13th month pay and other benefits have a ₱90,000 non-taxable ceiling.
If the applicable combined benefits exceed the ₱90,000 ceiling, the excess may become taxable.
For example:
If qualified 13th month pay and other benefits total ₱70,000, they remain within the ₱90,000 ceiling.
If they total ₱110,000, the amount exceeding the applicable ₱90,000 ceiling may form part of taxable compensation, subject to the relevant rules.
What About Minimum Wage Earners?
Minimum Wage Earners or MWEs have special tax treatment.
BIR identifies the statutory minimum wage of qualified MWEs as non-taxable compensation. It also separately recognizes certain holiday pay, overtime pay, night-shift differential and hazard pay received by MWEs as non-taxable under the applicable rules.
The statutory minimum wage itself varies by region, so don’t use one nationwide salary figure when determining whether someone qualifies.
Withholding Tax Is Not Another Separate Income Tax
Minsan nakakalito ang term na “withholding tax.”
Hindi ito simpleng additional tax na idinadagdag sa income tax.
For employees, the employer calculates and deducts the required withholding tax from compensation and remits it to BIR. BIR regulations also provide for year-end adjustment of tax withheld against the employee’s annual tax computation.
That’s why your monthly deduction and final annual computation should not be treated as two unrelated taxes.
Can You Calculate Your Tax Online?
Yes.
BIR provides an official Withholding Tax Calculator for Employees Earning Purely Compensation Income.
The calculator allows information such as payroll period, basic salary, allowances, supplementary compensation, non-taxable compensation and mandatory contributions to be entered.
For a real payslip, this is much safer than simply multiplying your gross monthly salary by a tax percentage.
Frequently Asked Questions
Tax-free ba kapag below ₱250,000 ang annual income?
For the graduated individual income-tax table, taxable income not over ₱250,000 is subject to zero income tax.
Remember that the key term is taxable income, not simply the number printed as gross salary.
Kapag ₱30,000 ang sweldo, 15% ba ng buong salary ang tax?
No.
The tax system uses brackets and formulas. For the annual ₱250,000–₱400,000 bracket, the 15% applies to the excess over ₱250,000, not the entire taxable income.
Taxable ba ang buong 13th month pay?
Not necessarily. BIR recognizes a ₱90,000 ceiling for 13th month pay and other benefits, subject to the applicable rules.
Bakit mas mataas ang withholding tax ko sa ibang buwan?
Possible reasons include bonuses, commissions, overtime, other taxable supplementary compensation or payroll adjustments. BIR’s withholding rules distinguish regular from supplementary compensation.
Final Takeaway
The easiest rule to remember is:
Annual taxable income up to ₱250,000 → no income tax under the current graduated table.
Above ₱250,000, the Philippines uses graduated tax brackets ranging from 15% to 35%, but the higher percentage does not automatically apply to your entire salary.
So kapag gusto mong malaman ang tunay na tax sa sweldo mo, don’t look at basic salary alone.
Check your taxable compensation, mandatory contributions, bonuses and other benefits, then compare the result with the appropriate BIR withholding table.
Information checked: September 14, 2026.
PINOY GUIDE is an independent informational website and is not affiliated with or operated by the Bureau of Internal Revenue or the Philippine government. This article provides general information only and is not personalized tax advice. Tax treatment can differ depending on individual circumstances. Always verify important tax matters with BIR or a qualified tax professional.
Official Sources
Bureau of Internal Revenue — Revised Withholding Tax Table (January 1, 2023 onwards)
BIR Revised Withholding Tax Table
Bureau of Internal Revenue — Revenue Regulations No. 8-2018 / Individual Income Tax Rates
BIR Individual Income Tax Rate Rules
Bureau of Internal Revenue — Official Withholding Tax Calculator
BIR Withholding Tax Calculator
PINOY GUIDE

Comments 0
Be the first to comment..