Withholding Tax Philippines 2026: Paano Malalaman ang Tax Deduction Mo?
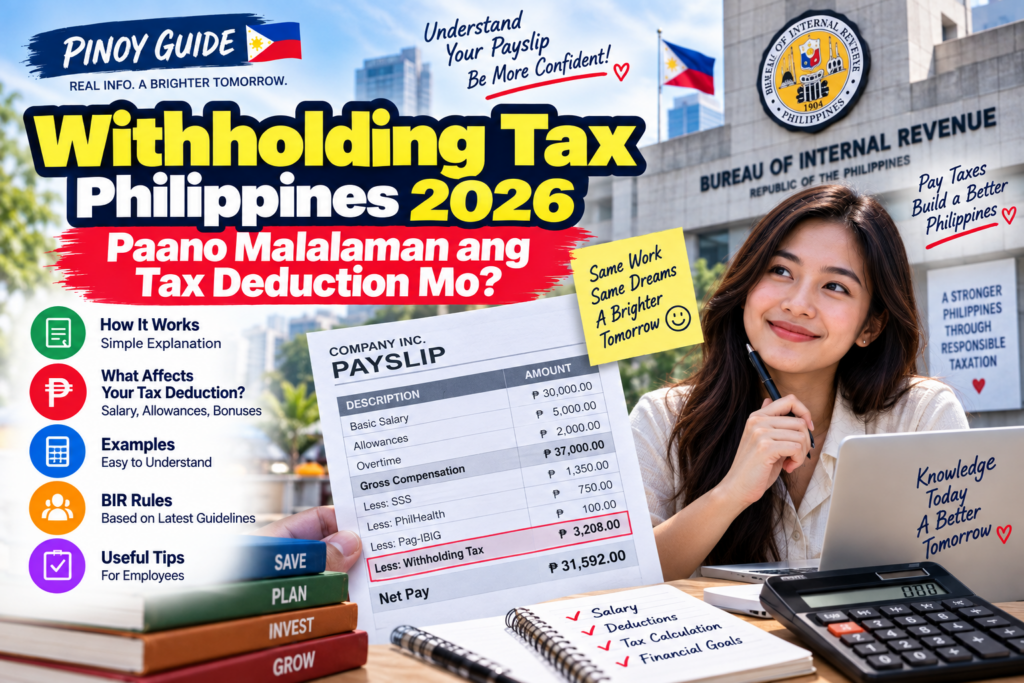
Every payday, may isang item sa payslip na maraming empleyado ang napapaisip:
Withholding Tax.
Para makita kung paano nakaaapekto ang withholding tax at mandatory contributions sa iyong take-home pay, gamitin ang Salary Calculator Philippines 2026.
Kung ₱30,000 ang salary mo, bakit hindi eksaktong pareho ang tax deduction buwan-buwan? Bakit may kasama pang SSS, PhilHealth at Pag-IBIG deductions? At kapag tumaas ang sweldo, buong salary ba agad ang tina-tax?
The answer becomes easier once you understand how withholding tax on compensation works.
Here’s a practical guide for Filipino employees in 2026.
What Is Withholding Tax?
Withholding tax on compensation is the income tax that an employer deducts from an employee’s taxable compensation and remits to the Bureau of Internal Revenue (BIR).
In other words, instead of waiting until the end of the year before collecting your income tax, part of the estimated tax obligation is already withheld through payroll.
BIR requires employers paying compensation to determine the amount using the prescribed withholding tax tables.
So kapag nakita mo sa payslip:
Withholding Tax: ₱XXX
hindi ito another government contribution similar to SSS, PhilHealth or Pag-IBIG.
It’s related to your income tax.
Gross Salary vs Taxable Compensation
Withholding tax is applied to taxable compensation, not automatically to the full gross salary. Mandatory employee contributions and applicable non-taxable compensation are considered before the correct payroll-period formula is used.
For the complete annual tax brackets, tax-free threshold and annual examples, see our BIR Income Tax Philippines guide.
Paano Kinukuwenta ang Withholding Tax sa Payslip?
BIR’s rules provide withholding tables according to the payroll period, including daily, weekly, semi-monthly and monthly payroll.
BIR Monthly Withholding Tax Table (2023 Onward)
For monthly payroll, apply the formula to monthly taxable compensation after applicable non-taxable items—not automatically to the employee’s headline gross salary.
| Monthly taxable compensation | Prescribed withholding tax |
|---|---|
| ₱20,833 and below | ₱0 |
| Over ₱20,833 to ₱33,332 | 15% of excess over ₱20,833 |
| ₱33,333 to ₱66,666 | ₱1,875 + 20% of excess over ₱33,333 |
| ₱66,667 to ₱166,666 | ₱8,541.80 + 25% of excess over ₱66,667 |
| ₱166,667 to ₱666,666 | ₱33,541.80 + 30% of excess over ₱166,667 |
| ₱666,667 and above | ₱183,541.80 + 35% of excess over ₱666,667 |
Let’s use a simplified monthly example.
Suppose your monthly taxable compensation after applicable non-taxable items is ₱30,000.
The monthly threshold corresponding to the first tax-free band starts at approximately ₱20,833.
For taxable monthly compensation above ₱20,833 but not over ₱33,332, the applicable rate from 2023 onward is 15% of the excess over ₱20,833.
So:
₱30,000 − ₱20,833 = ₱9,167
Then:
₱9,167 × 15% ≈ ₱1,375
The estimated withholding tax is therefore around:
Estimated withholding tax: approximately ₱1,375
This is a simplified illustration. Your actual payroll computation may differ depending on your real taxable compensation, payroll frequency, supplementary compensation and year-end adjustments.
What If Taxable Compensation Is ₱50,000?
Let’s try another simplified monthly example.
₱50,000 falls into the monthly bracket corresponding to annual taxable income over ₱400,000 but not over ₱800,000.
The formula is approximately:
₱1,875 + 20% of excess over ₱33,333
So:
₱50,000 − ₱33,333 = ₱16,667
20% × ₱16,667 ≈ ₱3,333
Add ₱1,875:
Estimated withholding tax: approximately ₱5,208
Again, this example assumes ₱50,000 is already taxable compensation, not simply the employee’s headline gross salary.
BIR’s official tax rules establish the 15%, 20%, 25%, 30% and 35% graduated rates for taxable years 2023 onward.
Bakit Hindi Pareho ang Tax Deduction Every Month?
Your withholding tax can change even if your basic salary remains the same.
Possible reasons include:
- Overtime pay, commissions and bonuses
- Taxable allowances or supplementary compensation
- Salary increase or payroll adjustment
- Changes in non-taxable benefits or mandatory contributions
BIR’s withholding rules require employers to determine total monetary and non-monetary compensation for the applicable payroll period before calculating taxable compensation.
So if you receive a large taxable bonus or commission in one payroll period, your withholding tax may also increase.
Other Payroll Items That Affect Taxable Compensation
SSS, PhilHealth and Pag-IBIG are separate mandatory contributions, not withholding tax. However, the employee shares are relevant when payroll determines taxable compensation.
Qualified 13th month pay and other benefits also have separate tax treatment, including the applicable ₱90,000 exemption ceiling. Check the BIR income tax guide for the broader rules.
What Is Year-End Adjustment?
Employers don’t simply calculate each month in complete isolation.
At year-end, the employer determines the employee’s annual taxable compensation and compares the income tax due with the cumulative amount already withheld during the year.
BIR rules provide for an adjustment when the tax computed differs from the cumulative withholding already deducted.
This can result in:
- Additional tax being withheld, or
- An adjustment for excess tax previously withheld.
That’s why December payroll can sometimes look different from previous months.
Under BIR RR No. 11-2018, annualized withholding procedure, excess compensation tax must be credited or refunded by the employer no later than January 25 of the following year. If employment ends before December, the regulation requires the refund with the employee’s last compensation payment during that year. Ask payroll for the annual computation and how the credit or refund appears on your payslip.
Example: ₱1,500 Excess Withholding
For a simplified full-year, compensation-only example, assume ₱360,000 is annual taxable compensation after applicable non-taxable items. Using the BIR annual rates effective from 2023 onward:
| Item | Amount |
|---|---|
| Annual taxable compensation | ₱360,000.00 |
| Annual income tax: (₱360,000 − ₱250,000) × 15% | ₱16,500.00 |
| Tax already withheld during the year | ₱18,000.00 |
| Excess withholding: ₱18,000 − ₱16,500 | ₱1,500.00 |
The ₱1,500 is a credit or refund in this example, not an automatic annual benefit. If the tax already withheld is lower than the annual tax due, the adjustment goes the other way. Your actual annual taxable compensation and cumulative withholding determine the result.
How to Check Your Own Payslip
When reviewing your payslip, don’t look only at the withholding-tax number.
Check the relationship between:
Gross/basic compensation → allowances and other compensation → mandatory contributions/non-taxable items → taxable compensation → withholding tax → net pay.
If something looks unusually high, compare the current payslip with the previous one.
- May overtime, commission o bonus ba ngayong payroll?
- May nadagdag bang taxable allowance?
- Nagbago ba ang basic salary o payroll period?
- May year-end adjustment o correction mula sa nakaraang cutoff?
Often, the difference can be explained by one of these items.
Use the Official BIR Withholding Tax Calculator
You don’t need to rely on random salary calculators found online.
BIR provides its own Withholding Tax Calculator, which allows taxpayers to estimate applicable withholding amounts.
This is particularly useful if you want to compare your own calculation with your payroll deduction.
For an actual discrepancy, however, ask your company’s payroll or HR department how they arrived at the taxable compensation used in the calculation.
Withholding Tax vs Income Tax
Income tax is imposed on taxable income, while withholding tax on compensation is the payroll mechanism used by the employer to deduct and remit that tax. Minimum Wage Earners have special non-taxable treatment, so ordinary payroll examples should not be applied to them without checking the applicable BIR rules.
Frequently Asked Questions
Bakit walang withholding tax sa payslip ko?
One possible reason is that your taxable compensation remains within the applicable tax-free range. Under the current annual graduated table, taxable income not exceeding ₱250,000 is subject to zero income tax.
Paano kung mukhang mali ang withholding tax ko?
Review your payslip first, compare it with BIR’s official calculator, and ask payroll or HR for the taxable-compensation computation if necessary. For unresolved tax questions, verify directly with BIR.
Final Takeaway
You don’t have to be an accountant to understand the tax deduction on your payslip.
Remember this basic idea:
Gross compensation is not automatically taxable compensation.
After applicable non-taxable items are considered, BIR’s withholding-tax rules and the correct payroll-period table are used to determine the amount withheld.
And if your tax deduction changes from one payday to another, don’t immediately assume there’s an error.
Check your taxable compensation, overtime, bonuses, commissions, allowances and payroll adjustments first.
For the most reliable estimate, use the official BIR calculator rather than an unofficial salary-tax website.
Original information check: October 6, 2026. Year-end excess withholding, refund timing and annual example reviewed: October 26, 2026.
PINOY GUIDE is an independent informational website and is not affiliated with, endorsed by, or operated by the Bureau of Internal Revenue or the Philippine government. This article provides general information and simplified examples, not individualized tax advice. Verify important tax matters with BIR or a qualified tax professional.
Official Sources
Bureau of Internal Revenue — Official Withholding Tax Calculator
BIR Withholding Tax Calculator
Bureau of Internal Revenue — Revenue Regulations No. 11-2018
BIR Withholding Tax Regulations
Bureau of Internal Revenue — RR No. 8-2018 Digest: Annual Income Tax Rates from 2023 Onward
BIR annual graduated income-tax rates
Bureau of Internal Revenue — Revised Withholding Tax Table (Effective January 1, 2023 onwards)
BIR Revised Withholding Tax Table — Annex E


Comments 0
Be the first to comment..